
Blue-Green Autonomy: How AI Is Driving the Future of Transportation
TL;DR
- Blue-green lighting is emerging as the industry-standard signal for autonomous vehicle operation, with SAE and regulators pushing for turquoise indicators to improve public trust and road safety.
- Major AV players including Waymo, Zoox, and Aurora are scaling driverless deployments in 2025-2026, while startups in robotaxis, trucking, and delivery continue to attract fresh funding.
- AI foundation models and generative simulation are now central to mobility development, accelerating testing, city planning, and in-vehicle experiences far beyond traditional driving stacks.
Why Blue-Green Means Go for Autonomy
Welcome back to TechCrunch Mobility. For years, autonomy has struggled with a simple problem: how do you know when a car is driving itself?
The answer increasingly appears to be blue-green. More specifically, a turquoise-colored light.
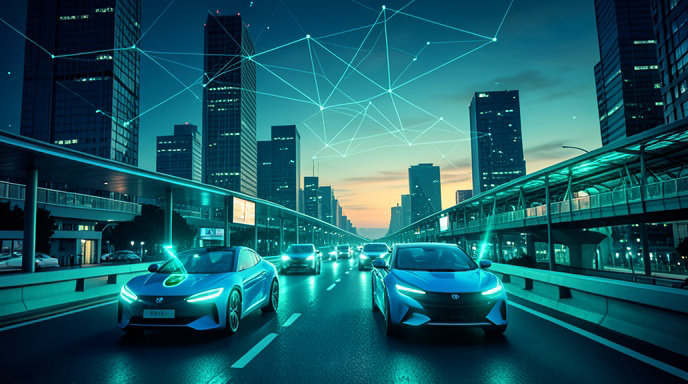
SAE International has recommended turquoise for automated driving system markers, and automakers including Mercedes-Benz, BMW, and Stellantis have been testing exterior turquoise indicator lights to signal when Level 3 conditional automation is engaged. In the U.S., California and Nevada have granted exemptions for Mercedes DRIVE PILOT turquoise marker lights, making it the first production system allowed to display them.
The logic is human-centered. Red means stop, amber means caution, white is headlights. Turquoise is distinct, visible at distance, and not already claimed by existing traffic signals. For pedestrians, cyclists, and first responders, a clear AV-active signal could reduce confusion around driverless cars stopped at intersections or pulling over.
Regulators and safety advocates see standardization as critical as Waymo and Zoox expand driverless operations with no one behind the wheel. Expect blue-green to become the visual shorthand for the new era of autonomy.
AV Breakthroughs: Robotaxis Go Mainstream
The past few weeks have underscored that robotaxis are no longer pilots.
Waymo continues to lead U.S. scale, now delivering well over 250,000 paid rides per week across Phoenix, San Francisco, Los Angeles, and Austin, with expanded service in Atlanta via Uber and testing in new cities including Nashville and Orlando. Its sixth-generation driver system on Zeekr-built vans is central to lowering unit cost.
Amazon-owned Zoox has moved from testing to commercial ramp-up, opening its purpose-built robotaxi with no steering wheel to public riders in Las Vegas and San Francisco, and building out its manufacturing footprint in California.
Meanwhile, Aurora Innovation hit a historic milestone with fully driverless Class 8 trucks hauling freight on public highways in Texas, operating between Dallas and Houston without a safety driver. Kodiak Robotics and Gatik are also pushing driverless trucking and middle-mile logistics toward commercialization.
Tesla remains the wildcard, launching its limited Robotaxi service in Austin using Model Y vehicles with safety monitors, while promising its Cybercab purpose-built two-seater for future high-volume production.
Startups to Watch in the Mobility Rush
Beyond the giants, a fresh wave of startups is reshaping transportation.
Applied Intuition, Nuro, and Saronic have raised large rounds at multi-billion dollar valuations to supply autonomy software, simulation tools, and autonomous ships. Nuro pivoted from delivery bots to licensing its Nuro Driver platform to automakers and mobility providers, landing partners including Uber, Lucid, and Toyota-backed Woven.
In delivery and sidewalk robotics, Serve Robotics and Starship Technologies are expanding Uber Eats partnerships across U.S. cities. In air mobility, Joby Aviation and Archer Aviation have completed piloted test milestones and secured military and airport partnerships as they target commercial eVTOL launch in 2026-2027.
Chinese players are moving fast too. WeRide, Pony.ai, and Baidu Apollo Go have expanded driverless permits in Beijing, Shanghai, Shenzhen, and the Middle East, while BYD and Xpeng push advanced driver assistance as standard.
The funding message is clear: autonomy infrastructure — chips, simulation, mapping, fleet management — is where venture money is flowing.
How AI Is Reshaping Mobility More Than Ever
AI is no longer just the perception stack. It is the whole product cycle.
Autonomous developers have shifted from modular pipelines to end-to-end foundation models trained on massive real-world and synthetic data. Waymo, NVIDIA, Tesla, and emerging players like Waabi and Wayve tout generative world models that can simulate rare edge cases — a child darting between cars, construction detours in rain — thousands of times overnight.
NVIDIA’s DRIVE Thor and Cosmos platforms, Qualcomm’s Snapdragon Ride, and Mobileye’s SuperVision are bringing large-model inference into production cars, enabling more capable Level 2+ highway and urban assist.
Inside the cabin, generative AI assistants are redefining the ride experience. Mercedes, BMW, Volkswagen, and Rivian are integrating LLM-powered voice assistants for navigation, maintenance, and in-car productivity.
Cities are using AI too, for curb management, traffic optimization, and transit planning, with digital twins modeling entire metro areas before a single robotaxi is deployed.
The takeaway: the race is no longer just about removing the driver. It is about who builds the smartest AI mobility platform — from cloud training to turquoise-lit street reality.

Get All The Latest Updates Delivered Straight To Your Inbox For Free!